
NOTE
Supply and Demand
English translation of the original VNote “Supply and Demand”, preserving its structure with only necessary small corrections.
This is a historical learning note and may contain outdated or incomplete understanding.
Note: The original VNote structure and wording are preserved. Only clear errors or statistical/institutional definitions that have changed are corrected minimally.
1. Demand
1.1. What It Is
- Demand is the quantity of a good that consumers are willing and able to buy during a given period at a given price level.
- Willing to buy: desire, or potential demand
- Able to buy: money
- Demand = desire + money
- If only desire is satisfied, it is potential demand.
- If both are satisfied, it is effective demand.
- The benefit of distinguishing effective demand from potential demand is to understand actual market demand.
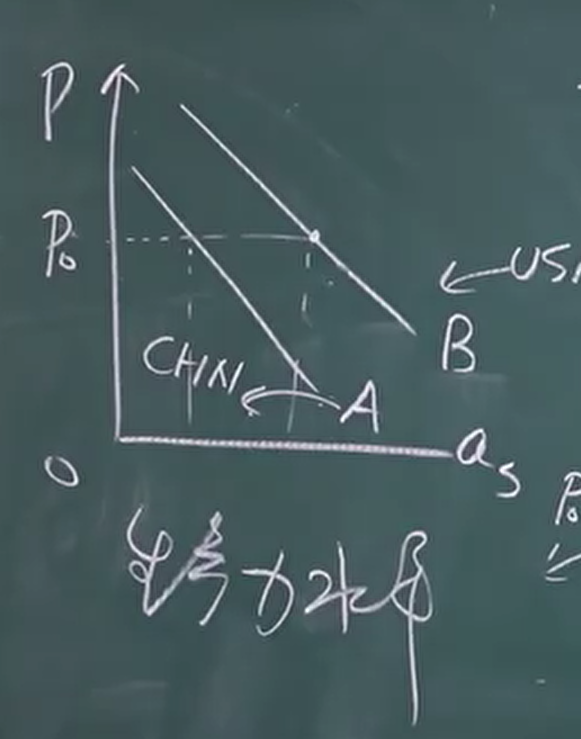
- For example, China has a large population but effective demand may be smaller, while the United States has a smaller population but effective demand may be larger.
1.2. Factors Affecting Demand
1.2.1. The Price of the Good Itself
- Price rises, quantity demanded falls.
1.2.2. Income Level
- Income rises, demand rises – normal goods.
- Income rises, demand falls – inferior goods.
1.2.3. Degree of Preference
1.2.4. Prices of Related Goods
- Price of good A rises, demand for B falls – complements -> firms are in a cooperative relationship.
- Price of good A rises, demand for B rises – substitutes -> firms are in a competitive relationship.
- Price of good A rises, demand for B is unchanged – independent goods.
1.2.5. Expectations About the Future
- Better future expectations, demand rises.
- Worse future expectations, demand falls.
1.3. Effect of Price on Demand
1.3.1. Law of Demand
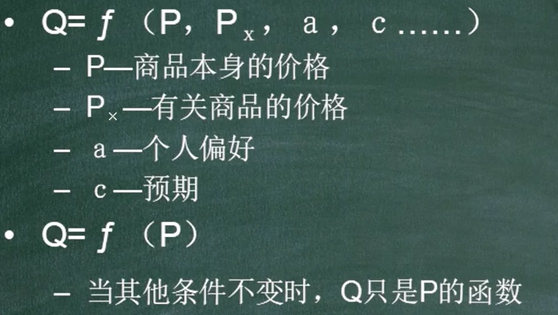
- Among the factors affecting demand, consider only the price of the good itself.
- Verbal description
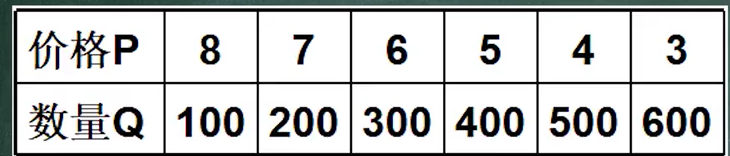
- Other things equal, the quantity demanded of a good changes inversely with the good’s own price.
- Demand schedule
- Demand curve
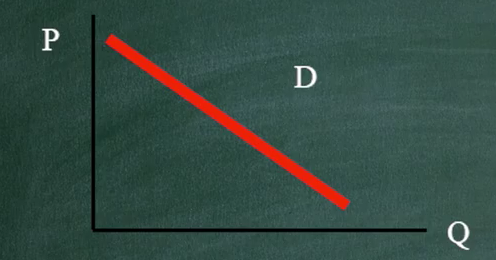
- It represents quantity demanded during a given period.
- Demand function
1.3.1.1. Market Demand
- Market demand = sum of individual demands.
- Therefore market demand also follows the law of demand.
1.3.2. Exceptions to the Law of Demand
- Price unchanged while demand keeps increasing
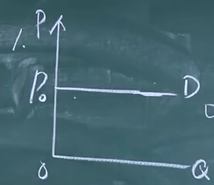
- For example, scarce materials such as gold.
- Demand does not change regardless of how high the price is
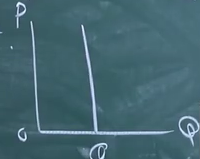
- Necessities such as salt and medicine.
- Price rises and demand rises
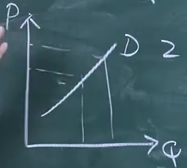
- Non-necessities such as luxury goods.
- Price rises and demand may fall or rise
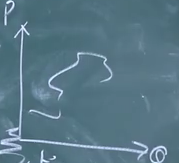
1.4. Effects of Other Factors on Demand
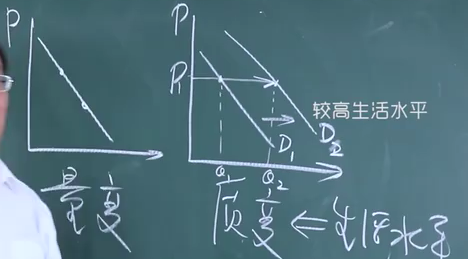
- Change in quantity demanded: change caused by the good’s own price – movement along the curve.
- Change in demand: change caused by non-price factors – shift of the curve.
2. Supply
2.1. What It Is
- Supply is the quantity of a good that producers are willing and able to provide during a given period at a given price level.
- A given period
- Willing to sell: willingness to sell, related to price
- Able to sell: output
- Supply = willingness to sell + output -> price + output
- When both conditions are met, it is effective supply (realized supply).
- When only one is met, it is potential supply (unrealized supply).
- The purpose of distinguishing effective and potential supply
- Measure producers’ actual income.
2.2. Factors Affecting Supply
- The price of the good itself
- Price rises, output rises.
- Product cost
- Cost rises, output falls.
- Technology level
- Technology improves, output rises.
- Productivity = (labor + capital + land) * technology
- Prices of related goods
- Prices of related goods rise, output falls.
- Producers’ objectives
- Mainly the following three:
- Profit maximization
- Total output maximization
- Average output maximization
- Mainly the following three:
- Future expectations
- Better economic expectations, output rises.
2.3. Effect of Price on Supply
2.3.1. Law of Supply
- Verbal description
- Other things equal, the quantity supplied of a good changes in the same direction as the good’s own price.
- Supply schedule
- Supply curve
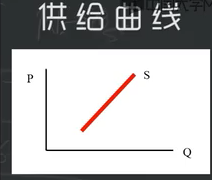
- It is defined over a period, not a single point in time.
- Supply function
- Supply = f(price, prices of other goods, cost, technology)
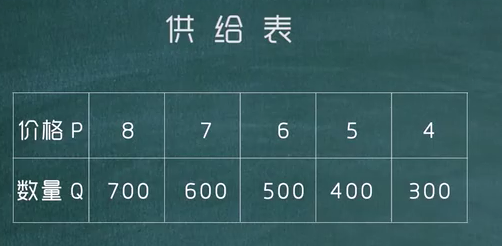
2.3.1.1. Market Supply
- Market supply = sum of individual supplies.
- Therefore market supply also follows the law of supply.
2.3.2. Exceptions to the Law of Supply
- Price unchanged while supply keeps increasing
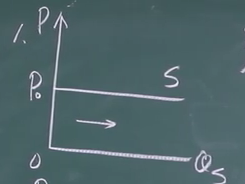
- Beverages
- Some public products/services: subway, bus, tap water, etc.
- Price keeps rising while supply remains unchanged
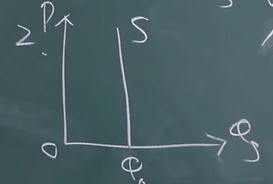
- Antiques, land, etc.
- Lower price, greater supply
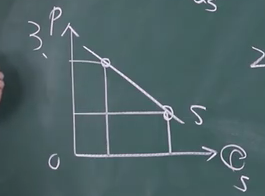
- Assembly-line work
- Price rises, supply may rise or fall
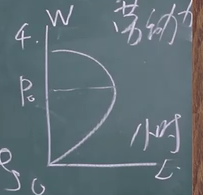
- Wages
2.4. Effects of Other Factors on Supply
- Change in quantity supplied: change caused by the good’s own price – movement along the curve.
- Change in supply: change caused by non-price factors – shift of the curve.
3. Market Equilibrium
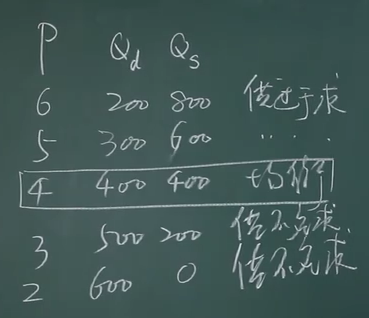
- Verbal description
- A market formed by demand and supply mainly has three states:
- Excess supply
- Equilibrium
- When demand equals supply, the market is in equilibrium. The corresponding price is the equilibrium price, and the corresponding quantity is the equilibrium quantity.
- Excess demand
- A market formed by demand and supply mainly has three states:
- Table method
- Graphical method
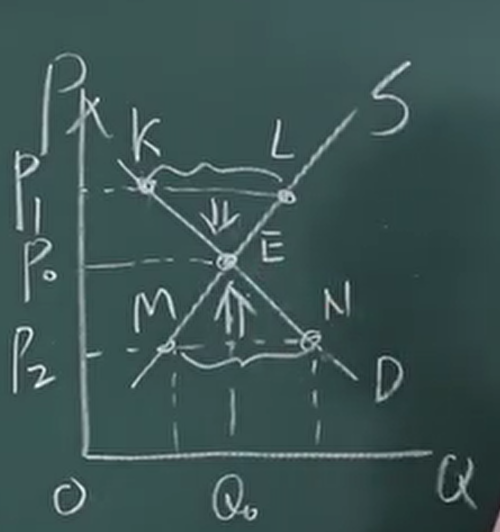
- E is the equilibrium point.
- K-L above E is excess supply.
- M-N below E is excess demand.
- Formula method
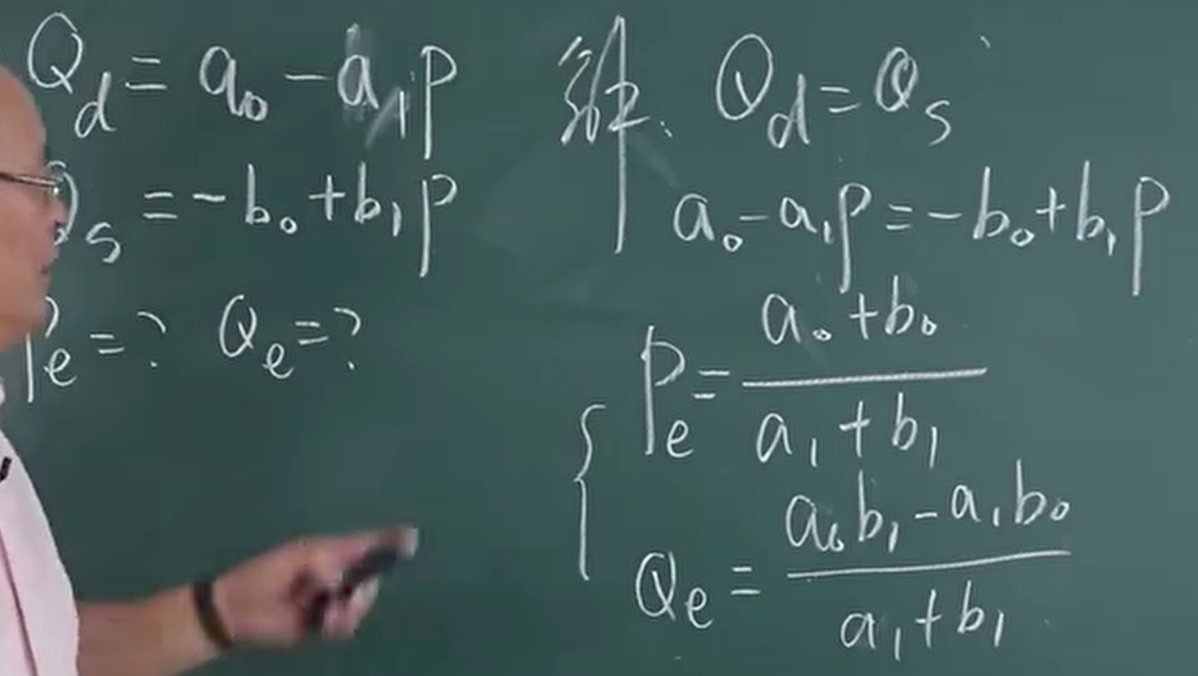
3.1. Changes in Market Equilibrium
- A change in demand alone causes equilibrium price and equilibrium quantity to move in the same direction.
- Demand increases -> equilibrium price rises, equilibrium quantity rises.
- Demand decreases -> equilibrium price falls, equilibrium quantity falls.
- A change in supply alone causes equilibrium price to move in the opposite direction and equilibrium quantity in the same direction.
- Supply increases -> equilibrium price falls, equilibrium quantity rises.
- Supply decreases -> equilibrium price rises, equilibrium quantity falls.
- Simultaneous changes in demand and supply produce more complex equilibrium changes.
- Supply increases, demand falls -> equilibrium price falls, equilibrium quantity is indeterminate.
- Supply decreases, demand rises -> equilibrium price rises, equilibrium quantity is indeterminate.
- Both increase -> equilibrium price is indeterminate, equilibrium quantity rises.
- Both decrease -> equilibrium price is indeterminate, equilibrium quantity falls.
3.2. Price Floors and Price Ceilings
- Price floor: a minimum price above the equilibrium price.
- Price ceiling: a maximum price below the equilibrium price.
3.3. Government Taxes
- Tax on producers -> production cost rises -> supply curve shifts left.
3.4. Government Subsidies
- Subsidy to producers -> production cost falls -> supply curve shifts right.