
NOTE
Cost and Revenue Theory
English translation of the original VNote “Cost and Revenue Theory”, preserving its structure with only necessary small corrections.
This is a historical learning note and may contain outdated or incomplete understanding.
Note: The original VNote structure and wording are preserved. Only clear errors or changed definitions are corrected minimally.
1. Explicit Costs and Implicit Costs
1.1. Explicit Costs
- Expenditures actually incurred during production are explicit costs.
- Also called accounting costs.
1.2. Implicit Costs
- Losses perceived by the operator during production are implicit costs.
- Also called opportunity costs.
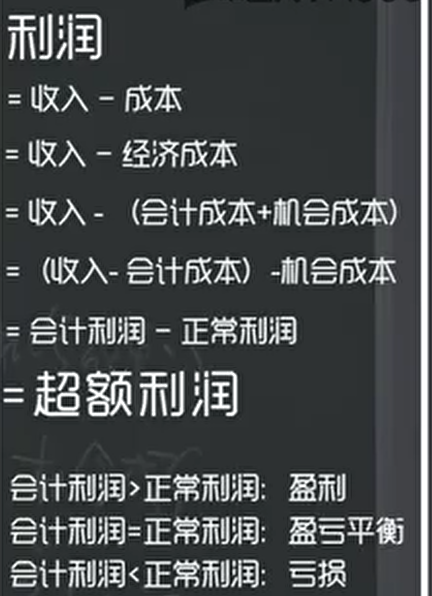
1.3. Economic Cost
- Economic cost = accounting cost + opportunity cost.
2. Short-Run Costs
2.1. Cost Function
- Reflects the relationship between cost and output.
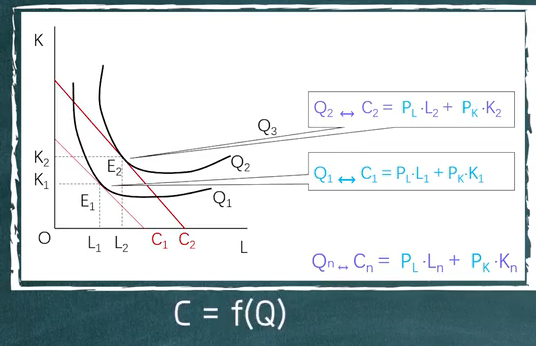
- This cost is the minimum cost and output is the maximum output.
- Short-run total cost = short-run fixed cost + short-run variable cost = spending on fixed factors + spending on variable factors.
- STC = TFC + TVC
2.2. Analysis
- Table method
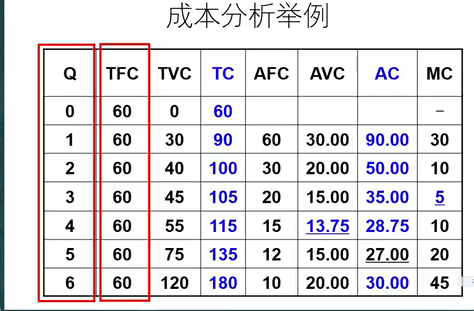
- TFC: total fixed cost
- TVC: total variable cost
- TC: total cost
- AFC: average fixed cost
- AVC: average variable cost
- AC: average cost
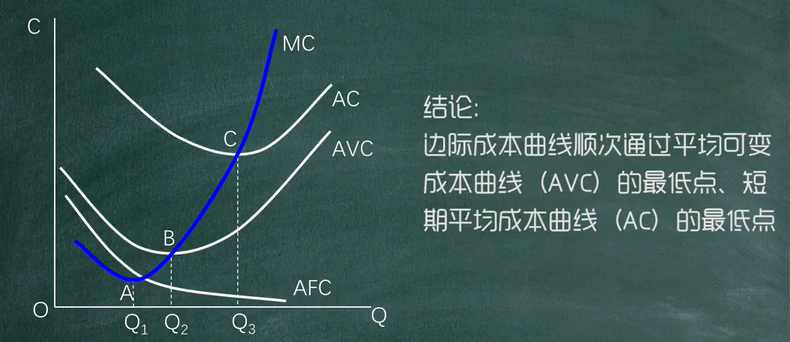
- MC: marginal cost
2.2.1. Total Cost
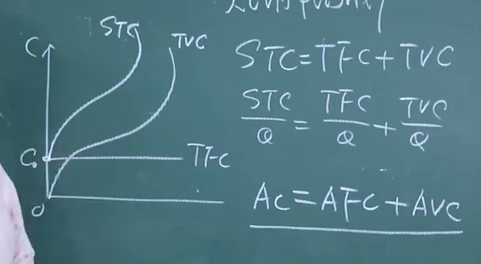
2.2.2. Average Cost
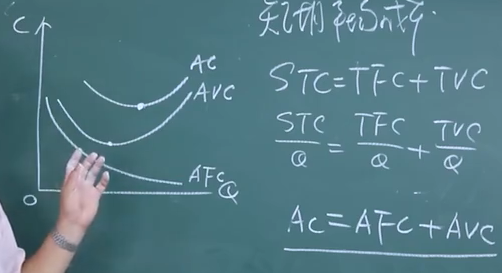
2.2.3. Marginal Cost Analysis
- Marginal cost first decreases and then increases.
- Formula: MC = change in total cost / change in output.
3. Long-Run Costs
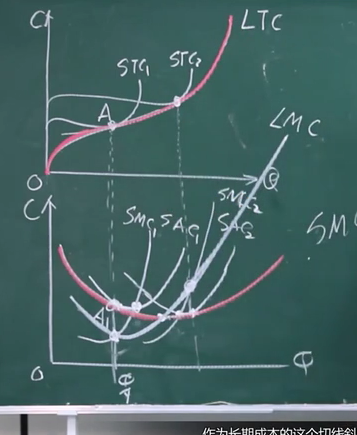
3.1. Long-Run Total Cost Analysis
- LTC and STC have similar curve shapes.
- Scale and cost
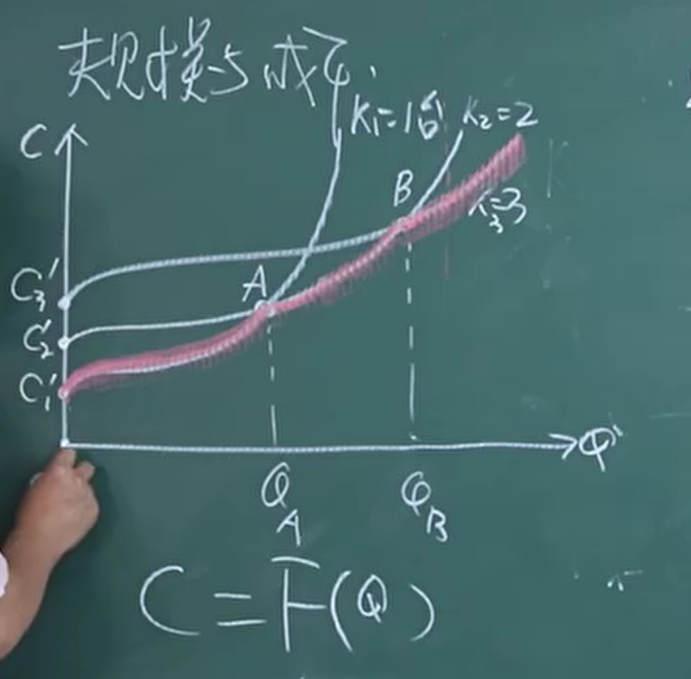
- Each point on the long-run cost curve is the minimum cost among different scales.
- All short-run cost curves lie above this long-run cost curve.
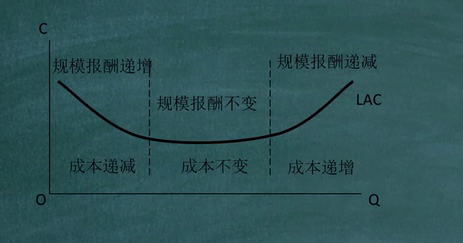
3.2. Long-Run Average Cost
- Both LAC and SAC are U-shaped.
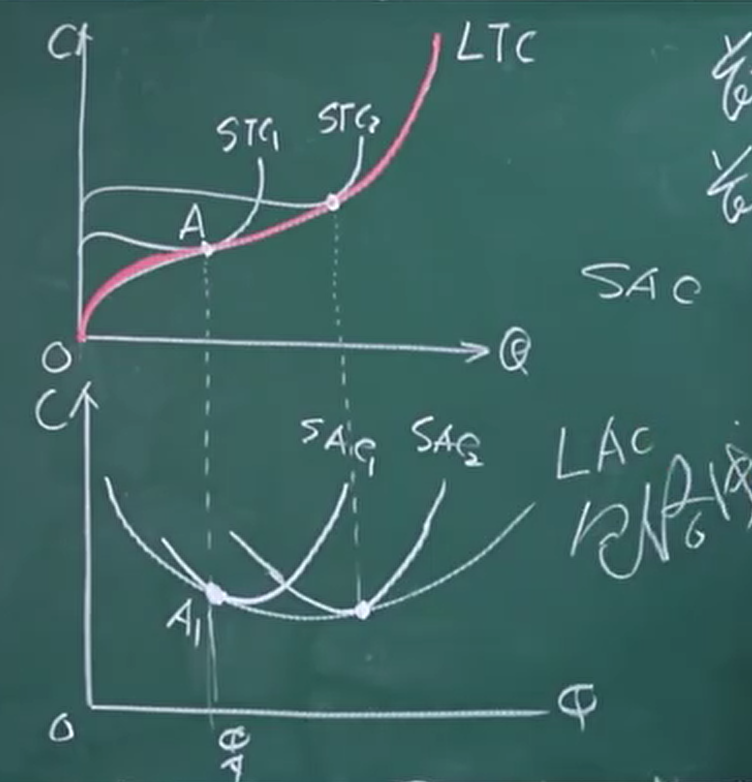
- Long-run average cost is the envelope of short-run average cost curves.
- Long-run cost is the minimum of short-run costs.
- Economies of scale means long-run average cost falls as output expands; it is related to, but not the same concept as, returns to scale.
3.3. Long-Run Marginal Cost
- LMC is also U-shaped and passes through the minimum point of LAC.
- At the output level determined by SAC and LAC, SMC = LMC.
4. Revenue and Profit
- Total revenue = price * output.
- Average revenue = total revenue / output = price.
- Marginal revenue = change in total revenue / change in output.
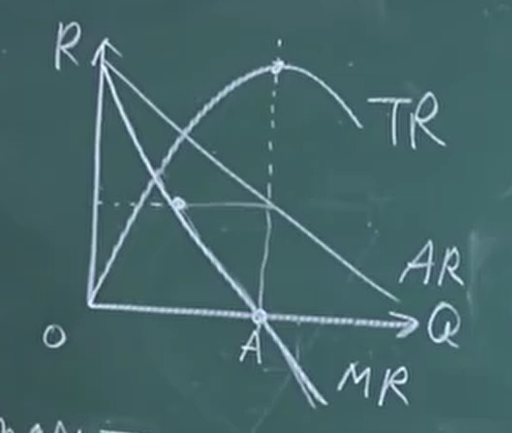
- The sum of marginal revenues equals total revenue.